Customized Cash Rewards or Unlimited Cash Rewards: Which Bank of America Card Fits Your Spending
One card rewards a category you pick and caps it. The other pays a flat rate on everything. The right answer depends entirely on where your money actually goes
The Answer First
Choose the Bank of America® Customized Cash Rewards credit card when a large share of your spending falls into one category you can nominate, and you stay inside the quarterly bonus cap. Choose the Bank of America® Unlimited Cash Rewards credit card when your spending is spread across many categories, or when you regularly spend past the cap. Both carry no annual fee, so the decision is about structure rather than cost. Confirm current rates, categories and caps with the issuer before deciding.
What’s the Difference Between Customized Cash Rewards and Unlimited Cash Rewards?
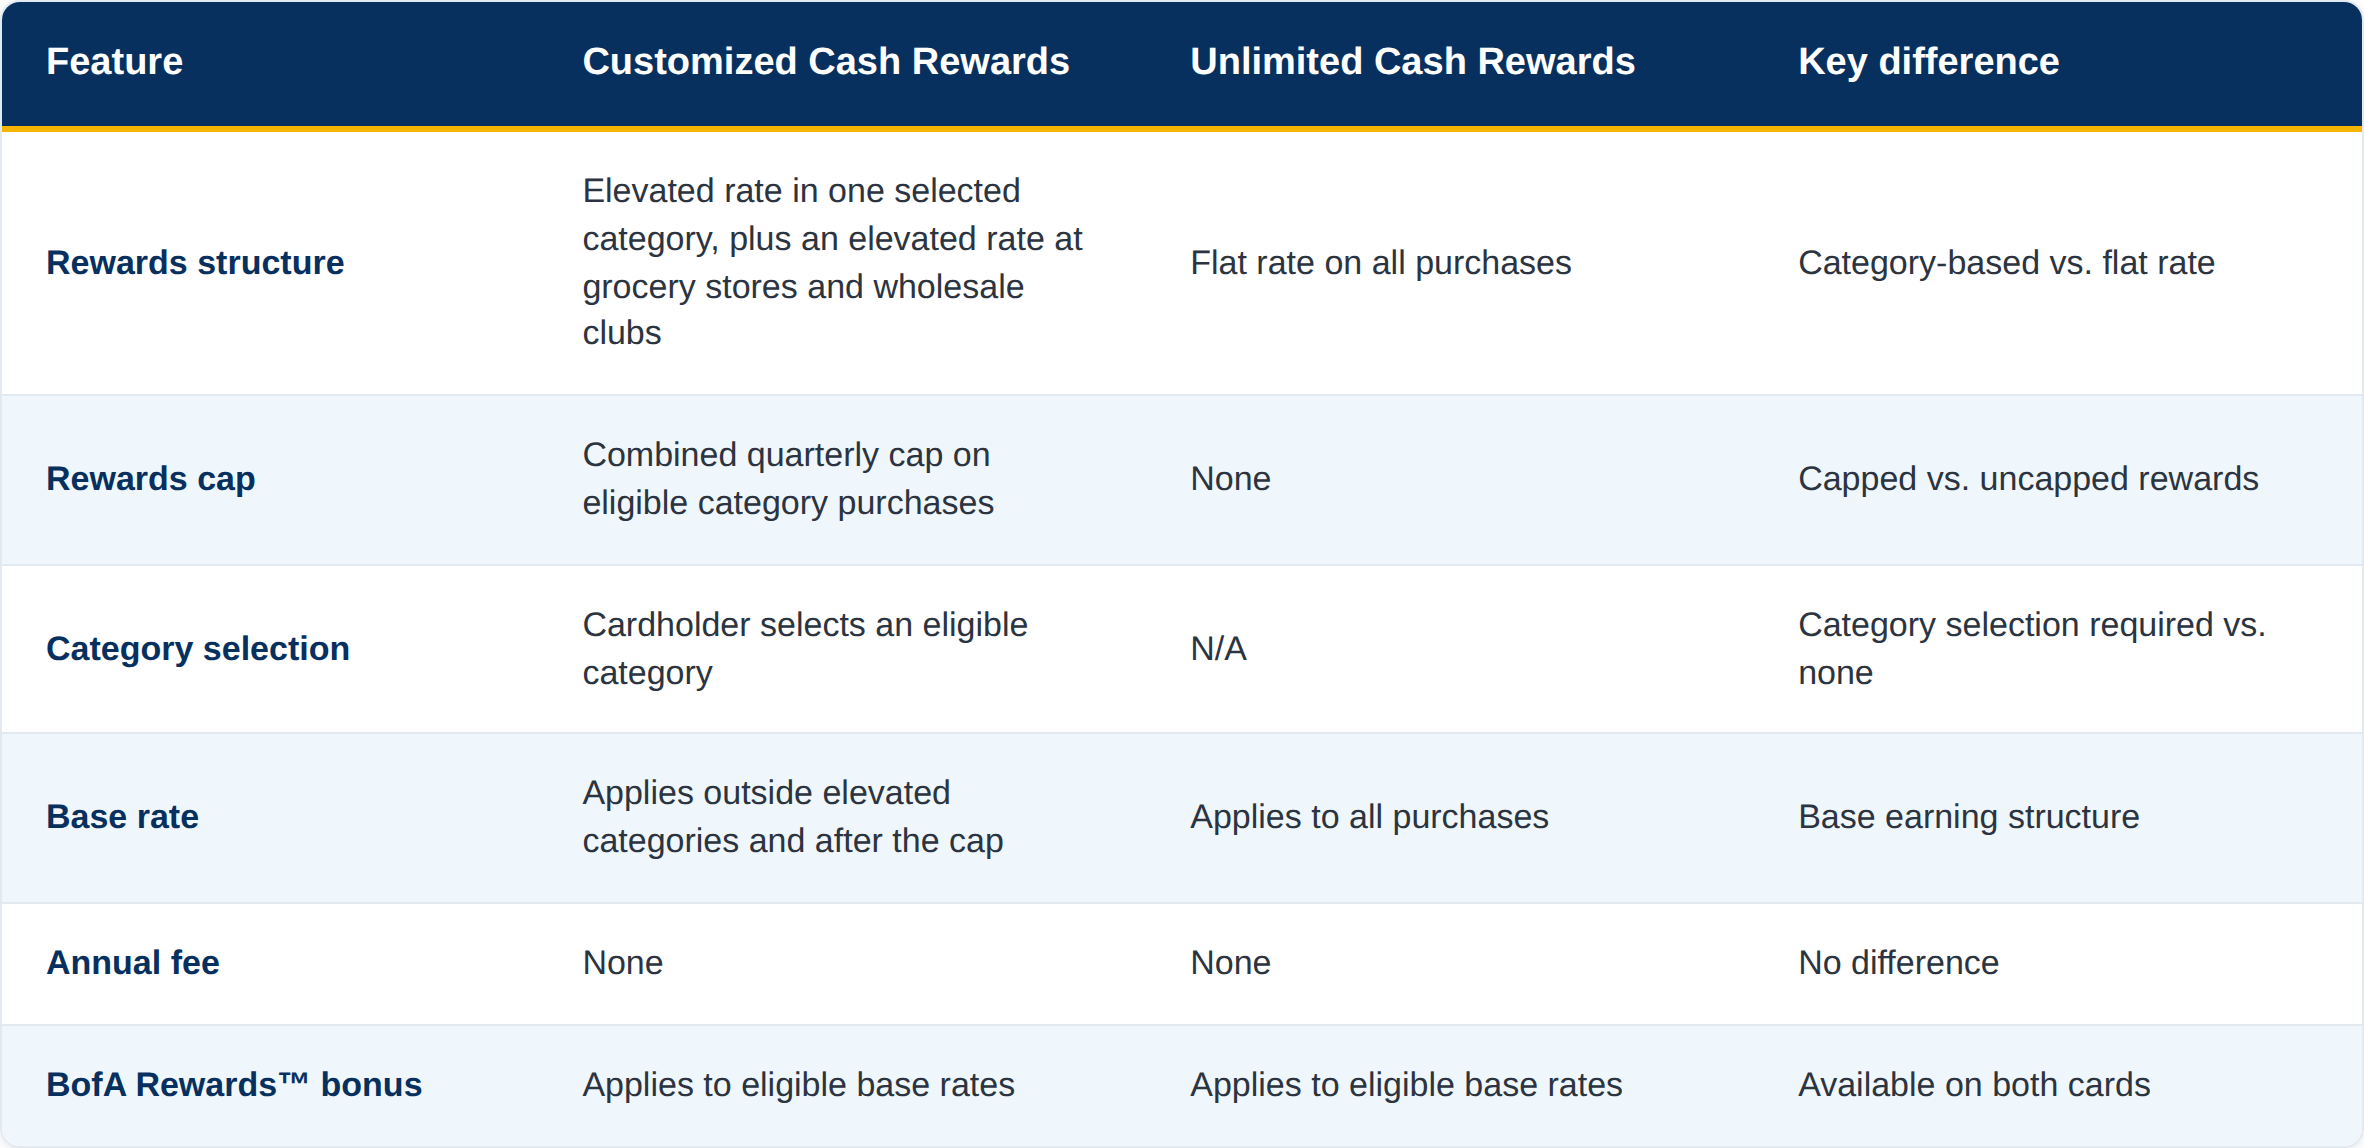
Comparisons of these two cards often focus on the earn rates. The structural difference is that one card concentrates a higher rate into a capped pool of spending and the other applies a single rate to everything without limit.
Once you frame it that way, the decision becomes arithmetic about your own spending rather than a judgment about which card is better. Neither is better. They are built for different spending shapes.
How Does the Customized Cash Rewards Cap Work?
On the Bank of America® Customized Cash Rewards credit card, the bonus cap is generally applied across the chosen category and the grocery and wholesale club category together, not separately to each. Cardholders who treat them as two independent allowances consistently overestimate what the card will return. Confirm the current cap structure with the issuer.
When Does Customized Cash Rewards Make Sense?
You Spend More in an Eligible Choice Category
The card rewards a category you select from a defined list. It works when a genuine share of your monthly spending consistently falls into one of those categories. If your largest category isn't on the list, the card's main feature isn't available to you.
Your Bonus Category Spending Stays Within the Cap
The cap is the binding constraint. If your combined bonus category spending sits comfortably below it each quarter, you capture the elevated rate on all of it. If you routinely exceed it, the additional spending earns the base rate, and the card's average return falls toward the flat rate alternative.
You’re Willing to Manage Your Choice Category
You can change the selection periodically, which sounds like an advantage but often isn't. Most people set it once and leave it. That is a reasonable strategy if the default matches your spending, and a costly one if it does not. Be honest about whether you will revisit it.
When Does Unlimited Cash Rewards Make Sense?
Your Spending Is Spread Across Categories
A flat rate on everything beats a higher rate on a small slice. If no single category dominates your statement, the flat card returns more with no attention required.
Your Spending Regularly Exceeds the Customized Cash Rewards Cap
Higher spenders hit the cap early in the quarter and then earn the base rate for weeks. A flat rate card has no such cliff. For consistent high spending, the uncapped structure is usually the stronger choice even though its headline rate is lower.
You Prefer a Flat Rate Card Without Category Management
There is no category to select, no cap to track, and no quarterly reset. For a card that sits behind recurring bills and everyday spending, that is a real advantage, not a consolation.
How to Compare Customized Cash Rewards vs. Unlimited Cash Rewards
- Pull three months of statements. Use your own data rather than an estimate. Category spending is routinely misremembered.
- Total the eligible categories per quarter. Add your best candidate category to grocery and wholesale club spending, since these share the cap.
- Compare that total against the cap. If it is consistently below, the category card is in play. If it is consistently above, the flat card is likely stronger.
- Apply your rewards tier multiplier to both. The tier lifts both cards proportionally, so it rarely changes which one wins, but it changes the size of the gap.
- Check the categories you cannot nominate. If a large part of your spending sits outside every eligible category, that spending earns the base rate on both cards and should be weighted accordingly.
Can You Have Both Customized Cash Rewards and Unlimited Cash Rewards?
Both cards carry no annual fee, which makes holding both a reasonable structure for some households: the category card for the nominated category up to the cap, the flat card for everything else and for spending above it.
This is a spending management decision, not a rewards trick. It only makes sense if you will route purchases deliberately and manage two accounts without carrying a balance on either.
Frequently Asked Questions
The Bottom Line
Pick the structure that matches your spending shape, not the higher advertised number. The Bank of America® Customized Cash Rewards credit card may make more sense when your spending is concentrated within the quarterly cap, while the Bank of America® Unlimited Cash Rewards credit card may make more sense when spending is spread across categories or regularly exceeds the cap. Review three months of your own statements before deciding, and confirm current rates, categories, and caps with the issuer.
Choose Your Next Step
- Compare Bank of America cash rewards cards
- See Bank of America cards with no annual fee
- Compare cash back cards across issuers
Sources
As Seen In


Trust & Secure