There’s a curious trend occurring among millennials and Gen Z, and we’re not referring to the latest TikTok dance challenge or Instagram filter. As Bloomberg reports, there’s a feeling of “money dysmorphia” taking root among these generations — the widespread feeling of financial unease, even when the numbers suggest stability.
Evidently, a significant chunk of these generations grapples with this skewed financial perception. Below, we explore how this phenomenon shapes their economic outlook — and how to strike a balance between reality and perception for a healthier financial mindset.
Understanding Money Dysmorphia
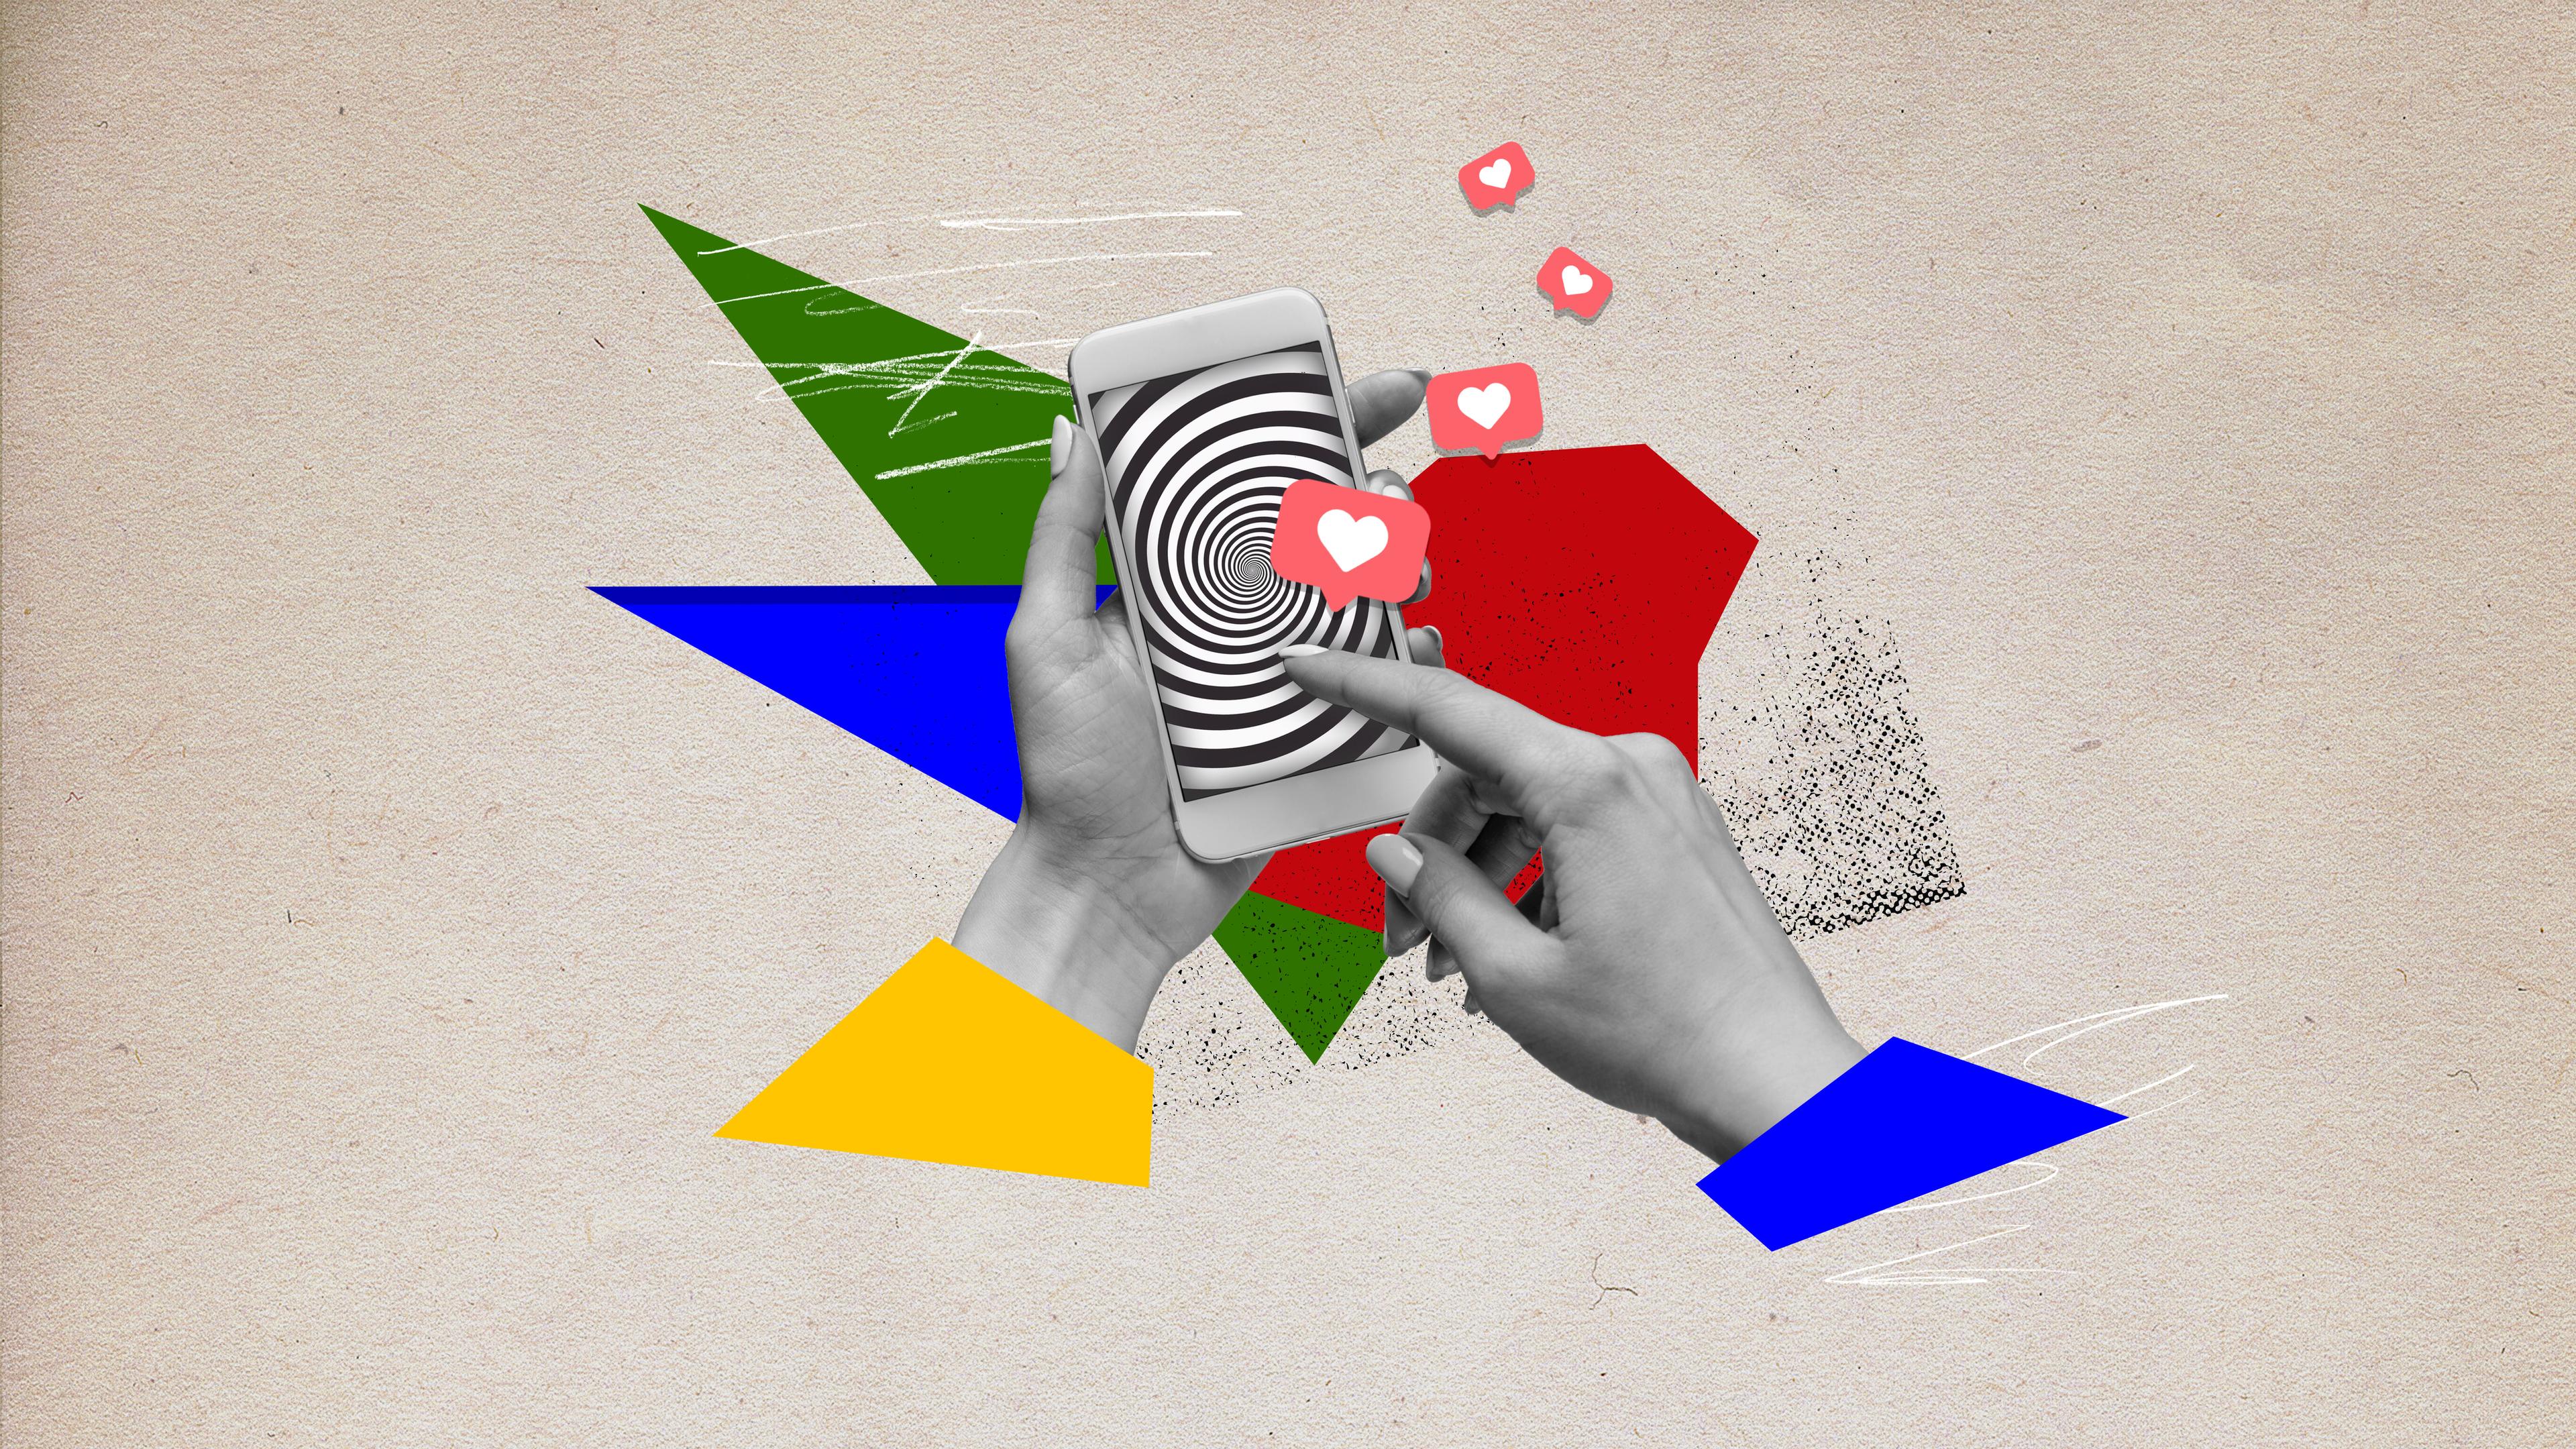
Having “money dysmorphia” is like putting on financial glasses that make your situation look worse than it is. Even when the numbers say you're doing okay, this mindset can cause feelings of financial insecurity.
money dysmorphia is like putting on financial glasses that make your situation look worse than it is
You might have a decent amount in your bank account, bills are paid, and life seems stable — but there's a persistent feeling that something's not quite right. That's the essence of "money dysmorphia" for many millennials and Gen Zers.
The Influence of Social Media
In the age of constant connectivity at a fingertip’s reach, platforms like Instagram, TikTok, and Twitter may contribute to “money dysmorphia.”
The curated lives presented on these platforms often showcase a glamorous world of luxury purchases, exotic vacations, and fashionable lifestyles. As young adults scroll through these images, the allure of such experiences can fuel a desire to emulate them.
Economic Challenges and Credit Use
Enter the plastic in our wallets — credit cards. The gap between the portrayed lifestyle and the financial reality can lead to impulsive spending and overreliance on credit cards to chase an illusion of affluence.
Part of the challenge is that millennials and Gen Zers may face uncertain futures, like not knowing whether they'll find stable jobs or how they'll afford education and homes. Credit cards can provide flexibility and support during these uncertain times, helping to fill in the financial gaps.
However, getting into debt becomes a real risk with credit card overuse, turning something meant to help into a source of stress down the road.
Credit Cards as a Double-Edged Sword
Using credit cards recklessly and going into debt can directly impact your credit score, which reflects your ability to manage borrowed money. If you struggle to repay your debts on time or accumulate debt, your credit score takes a hit.
A lower credit score makes it harder to secure future loans and might result in higher interest rates. So, when we talk about credit cards as a double-edged sword, one side of the blade is the potential harm to your credit if you're not mindful of your spending and repayment habits.
The other side of that double-edged sword? Credit cards can be excellent tools if you use them wisely. Instead of fueling “money dysmorphia” in response to perceived scarcity or a desire to measure up to unrealistic images of wealth, credit cards can help you manage money, grow your credit profile, and build stability.
Strategies for Financial Well-Being
The key is using credit cards responsibly without falling into traps that might compromise your financial well-being. Here are some strategies to mitigate money dysmorphia:
- Smart budgeting: Create and stick to a budget that outlines your income, expenses, and savings goals.
- Responsible credit card use: Only charge what you can afford to pay off each month.
- Set realistic goals: Define achievable financial goals based on your current situation to stay focused without succumbing to the pressure of unrealistic standards.
- Financial education: Learn the basics of personal finance. The more you know about managing money, the better equipped you are to make informed financial decisions.
- Professional advice: Consult a financial advisor for tailored guidance on budgeting, investing, and managing debt.
- Emergency fund: Build an emergency fund covering three to six months of expenses. Having a financial safety net reduces stress and minimizes reliance on credit cards during tough times.
Conclusion: Striking a Balance
Getting your finances in order is a balancing act — using credit for what you need now but avoiding a big pile of debt. This aspect is especially true for many millennials and Gen Zers learning how to make their money work for them.
It's clear that keeping a balanced view of credit and money is essential for tackling "money dysmorphia." Understanding that credit cards can help but also cause stress is a big step. By budgeting smartly, learning about money, and making wise choices with credit cards, you can set yourself up for a stable financial future.
As Seen In


Trust & Secure